Carbon removal markets offer the construction industry a new toolset for reducing emissions, and financing investments in low-carbon technologies. For concrete manufacturers, these markets represent both a challenge and a business opportunity. The sections below address the most important questions construction industry professionals are asking about carbon credits, carbon pricing, and carbon removal in practice.
What are carbon removal markets and how do they work?
Carbon removal markets are trading systems where organisations buy and sell verified credits that represent the permanent removal of carbon dioxide from the atmosphere. Unlike carbon avoidance, removal credits represent CO₂ that has been actively extracted from the atmosphere and stored in a durable, measurable way.
These markets operate across two main structures. Compliance markets are regulated by governments and require certain industries to account for their emissions within legal frameworks. Voluntary carbon markets operate independently, allowing companies to purchase and sell removal credits to meet their own climate commitments, to support low-carbon strategies, or to respond to investor and customer expectations.
Carbon credits must meet several quality criteria. The removal must be additional, meaning it would not have happened without the specific intervention. It must be permanent, meaning the stored carbon will not return to the atmosphere. It must be quantifiable through verified measurement, and it must be certified by an independent body.
Why is the construction industry a major target for carbon removal?
The construction industry is a major target for carbon removal because it is one of the largest sources of greenhouse gas emissions globally, and concrete production sits at the centre of that challenge. Cement, the binding material in concrete, releases significant CO₂ during manufacturing, making it one of the most emission-intensive industrial processes in the world.
At the same time, construction materials offer a physical pathway for storing carbon permanently. Concrete, in particular, has the structural capacity to mineralise CO₂ into stable carbonate compounds that remain locked in the material for centuries. This means the construction industry is not only a target for emission reduction but also a potential vehicle for active carbon removal at scale.
Precast concrete production is especially well positioned within this context. Precast facilities use controlled curing environments, which makes it technically feasible to introduce CO₂ into the curing process in a precise and measurable way. This controllability is important for meeting the verification standards that carbon removal markets require. The combination of high emission volumes and physical storage potential makes concrete manufacturing a promising sector for credible, large-scale carbon removal activity.
How can concrete manufacturers earn carbon credits?
Concrete manufacturers can earn carbon credits by permanently mineralising CO₂ into their products during the curing process and having that storage verified and certified. The credits generated represent durable carbon dioxide removal, which can then be sold to organisations seeking high-integrity offsets or used to improve the manufacturer’s own carbon reporting.
For the credits to be marketable, they must pass independent verification. This means the production process, measurement methodology, and storage claims are reviewed by a third-party certifier against an established standard. Carbonaide’s CDR credits, for example, are certified under Isometric’s module for CO₂ storage via carbonation in the built environment. This kind of certification gives buyers confidence that the credits represent genuine, permanent removal rather than an accounting adjustment.
Concrete manufacturers have two main options for monetising the carbon storage they generate. They can apply the stored carbon as a reduction in the carbon footprint of their own products, which improves the environmental product declarations they provide to construction clients. Alternatively, they can sell the credits on voluntary carbon markets to third-party buyers, creating a new revenue stream that helps offset the cost of adopting CO₂ curing technology.
What’s the difference between carbon avoidance and carbon removal in construction?
Carbon avoidance refers to emissions that are prevented from occurring, while carbon removal refers to CO₂ that is actively extracted from the atmosphere and stored permanently. In construction, both approaches exist, but they are not equivalent in terms of climate impact or market value.
Carbon avoidance in construction
Carbon avoidance credits in construction typically come from reducing the amount of cement used in a concrete mix, switching to supplementary cementitious materials such as slag or fly ash, or improving energy efficiency in production. These actions lower the carbon footprint of the product compared to a conventional baseline. The credits represent emissions that did not happen, not carbon that was removed. Avoidance has real value, but avoidance alone is not sufficient to reach genuine neutrality.
Carbon removal in construction
Carbon removal credits, by contrast, represent CO₂ that has been taken out of the atmosphere and stored in a durable form. In concrete manufacturing, this happens for example through CO₂ mineralisation during curing. Once mineralised into concrete, it is permanently bound as carbonate minerals.
Removal credits are increasingly preferred by serious buyers in voluntary carbon markets because they address the atmospheric stock of CO₂ rather than simply slowing the rate of new emissions. For concrete manufacturers, the ability to generate verified removal credits represents a meaningful competitive advantage.
How could carbon pricing change the economics of concrete production?
Carbon pricing could significantly change the economics of concrete production by making high-emission processes more expensive and creating financial incentives for producers who reduce or remove CO₂. As emission costs rise, manufacturers face increasing pressure on margins. Verified carbon removal credits then offer a new way of financing investments in low-carbon technologies.
In regions where compliance carbon markets already operate, large industrial emitters pay for each tonne of CO₂ they release above a permitted threshold. While concrete producers are not always directly covered by these schemes today, the regulatory direction is toward broader coverage over time.
There is also a downstream effect on procurement. Construction clients, particularly in the public sector and among large developers with their own net-zero commitments, are beginning to specify lower-carbon concrete in tenders. Carbon storage enables products with a verified, lower carbon footprint. For concrete producers, this means that the ability to demonstrate a measurable, certified carbon footprint becomes a commercial differentiator rather than a marketing claim.
What should construction companies do to prepare for carbon markets?
Construction companies preparing for carbon markets should focus on three areas: understanding their current carbon footprint, building the measurement infrastructure needed for verified reporting, and evaluating which carbon removal or reduction pathways are technically and economically viable for their production processes.
The starting point is accurate measurement. Carbon markets require verified data, not estimates. Concrete manufacturers need to know how much CO₂ is embedded in each product type and how that footprint is calculated. Environmental product declarations provide one framework for this, but they need to be supported by reliable, process-level data rather than industry averages.
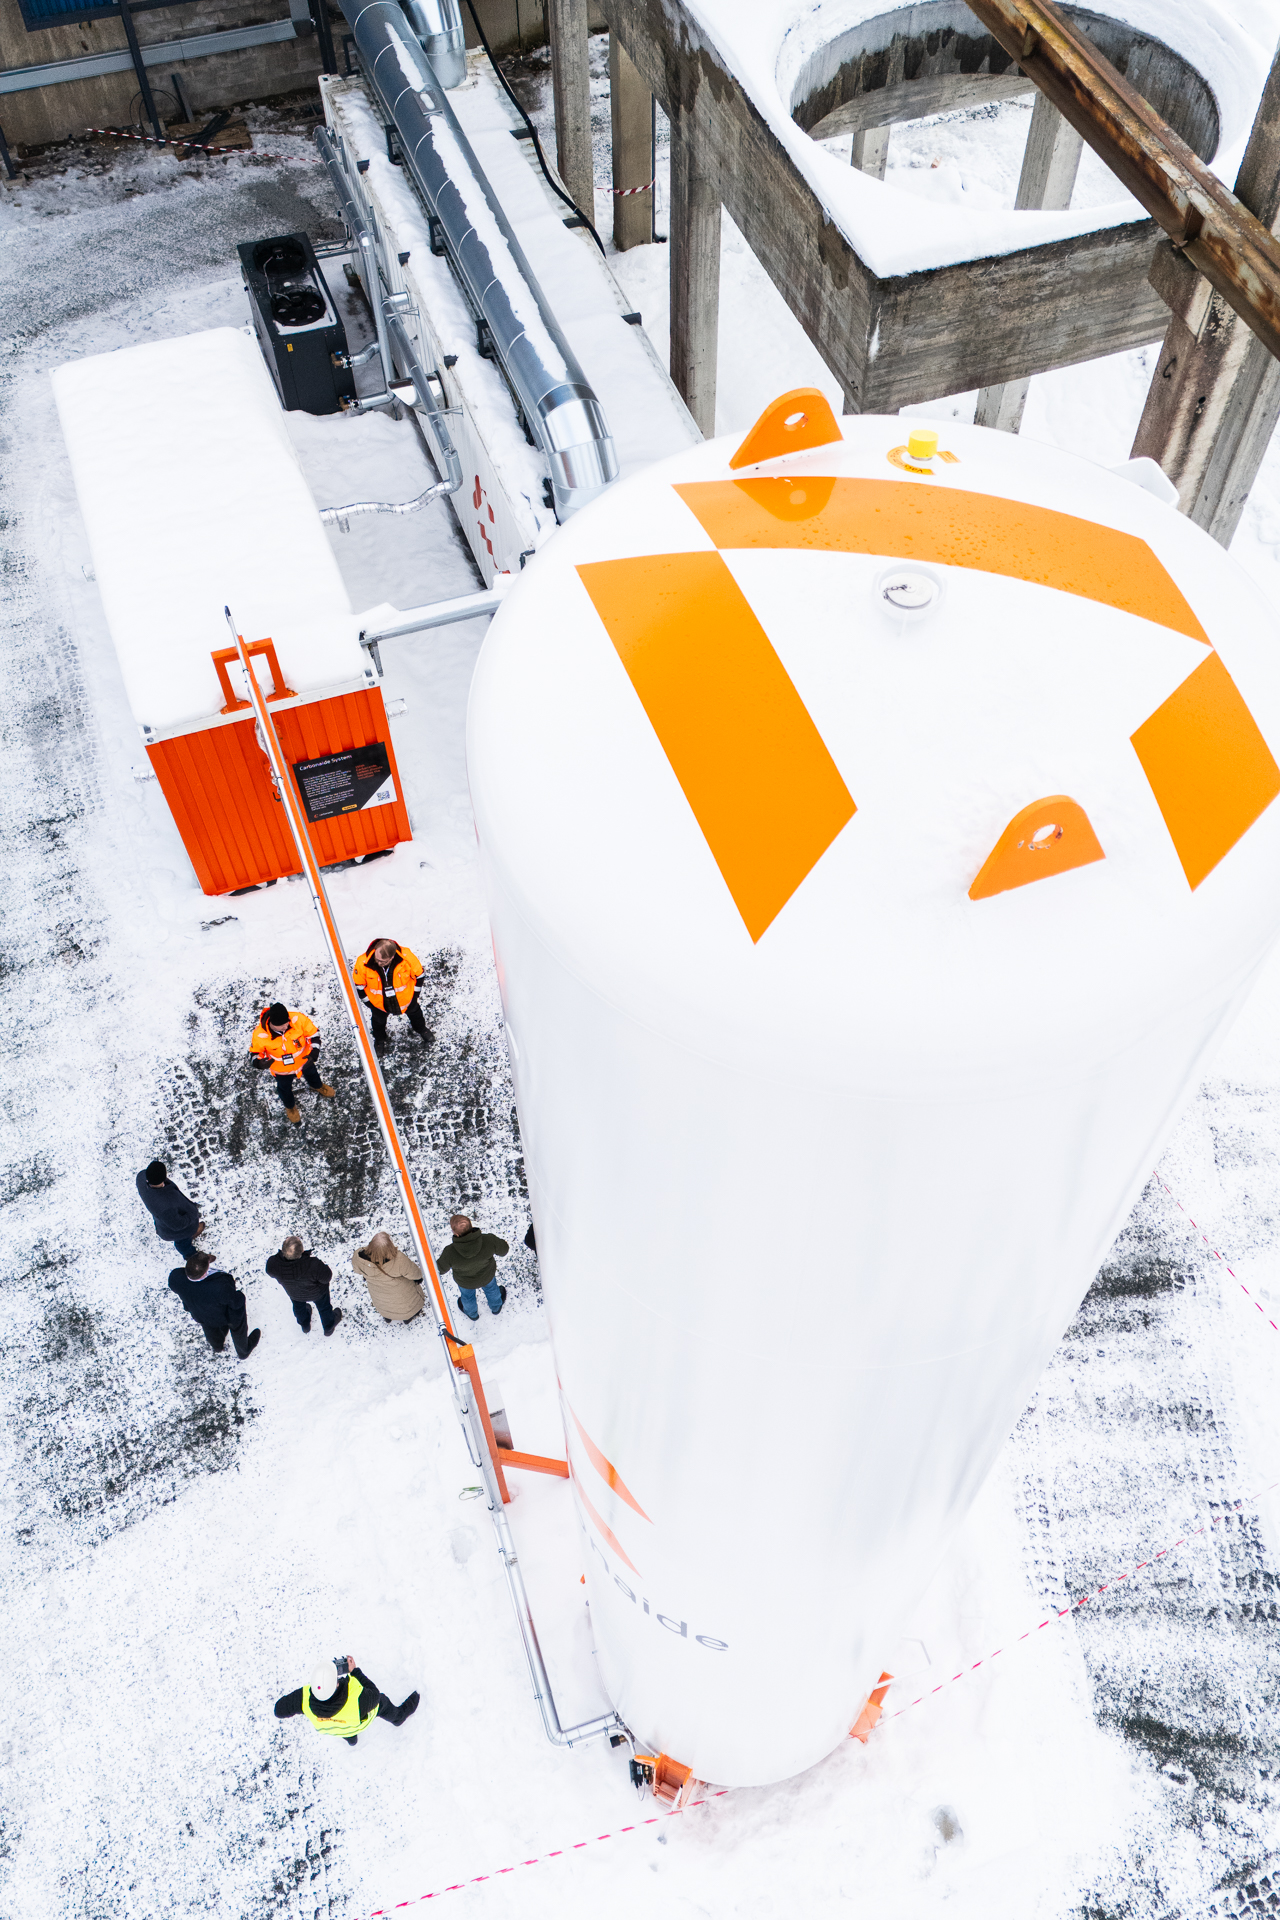
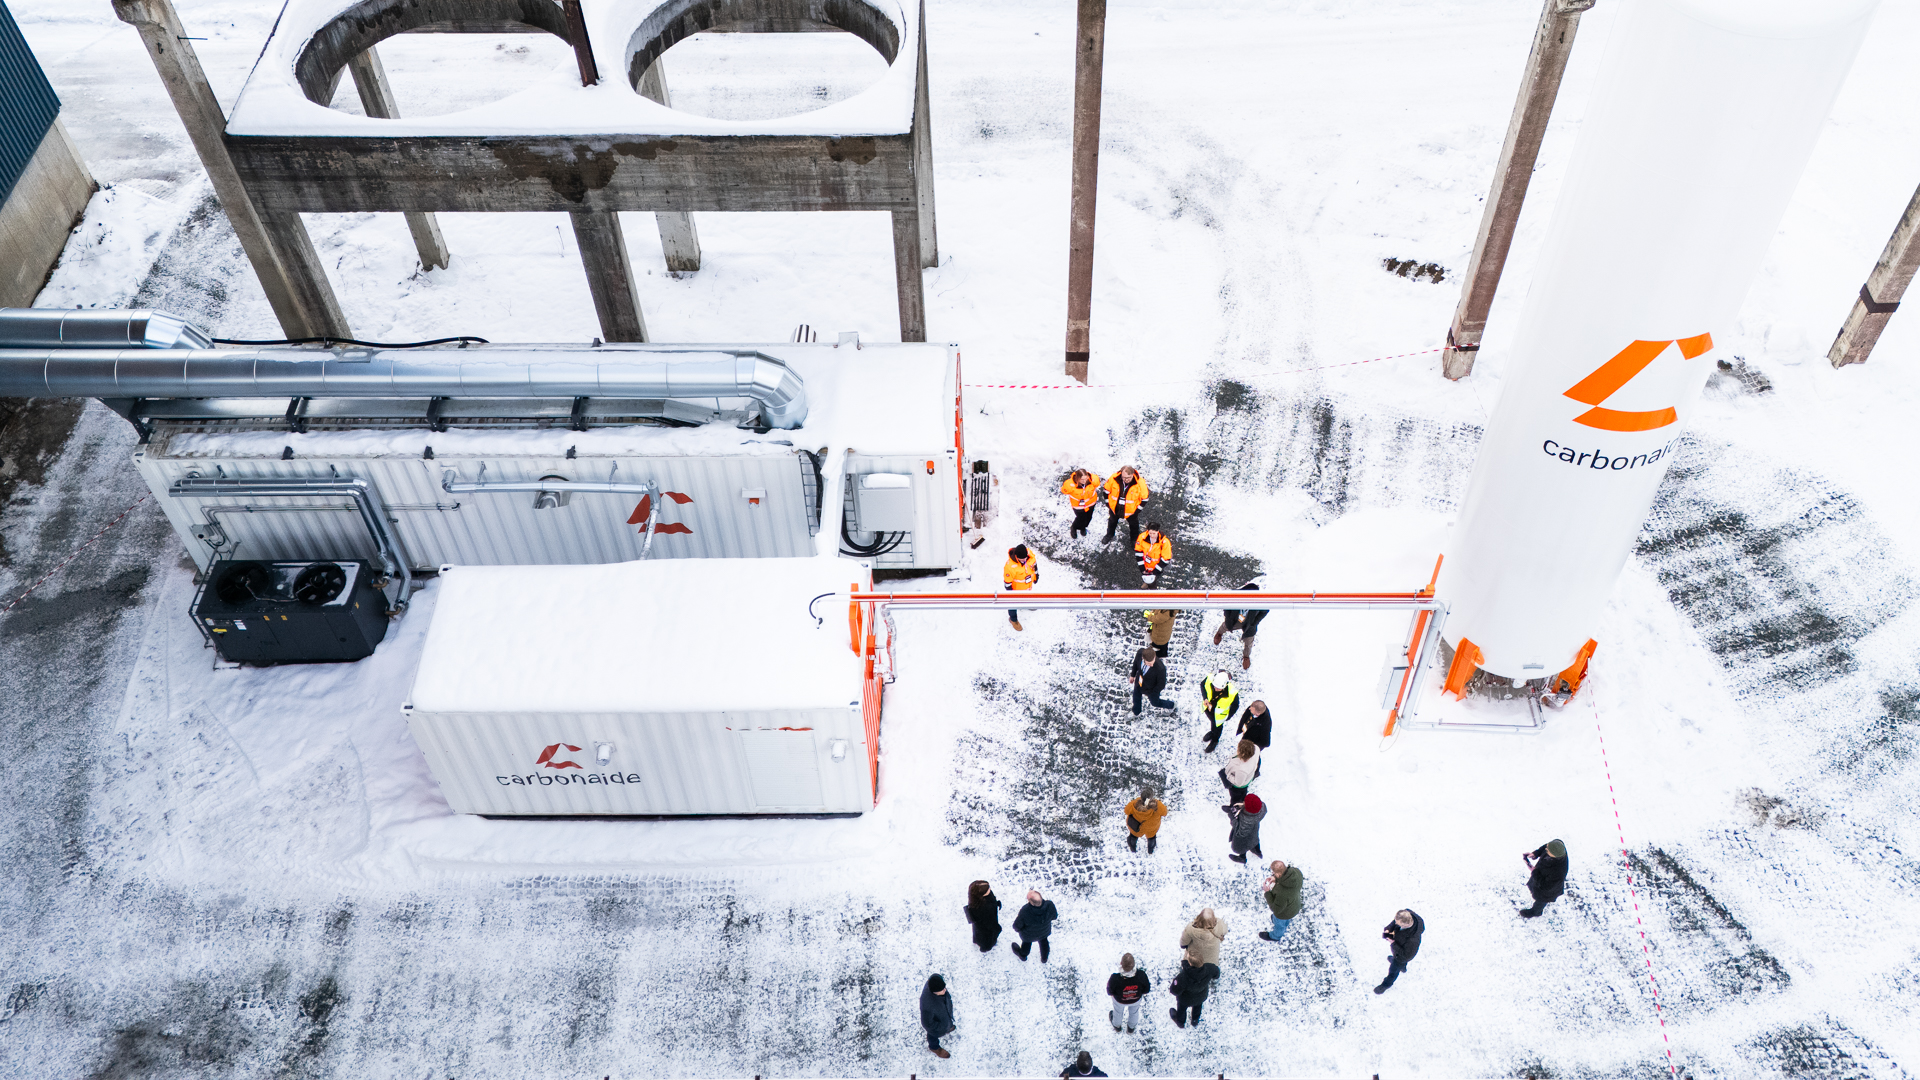
The next step is identifying which interventions are compatible with existing production. For precast producers with separate curing chambers, CO₂ mineralisation is a technically accessible option that does not require rebuilding the production line. The Carbonaide CO₂ Curing System is designed to integrate with new facilities or retrofit into existing curing chambers, which lowers the barrier to adoption.
Producers should also consider the certification pathway early. Generating carbon credits requires more than reducing emissions: it requires a documented, auditable process that meets the additionality, permanence, and quantification standards of a recognised certification body. The Carbonaide Service Platform supports this by managing CO₂ flow data, producing the documentation needed for carbon credit certification, and connecting producers with CDR partners who handle verification.